GREEK / 01
Delta
Delta measures the estimated change in an option’s price for a one-unit change in the underlying asset, assuming other variables remain constant. Call delta is generally positive. Put delta is generally negative.
The US options market is one of the world’s deepest and most liquid derivatives markets. It provides information about positioning, volatility expectations, hedging activity and changing market sentiment.
Interest rates, Treasury yields, corporate earnings and macroeconomic developments can all influence option prices. Monitoring these factors together can provide a more complete view of market conditions.
Data and analytical material are provided by TrueScale, GB.
Reproduction or publication requires appropriate source
attribution. All rights reserved.
Report issues or request data:
[email protected]
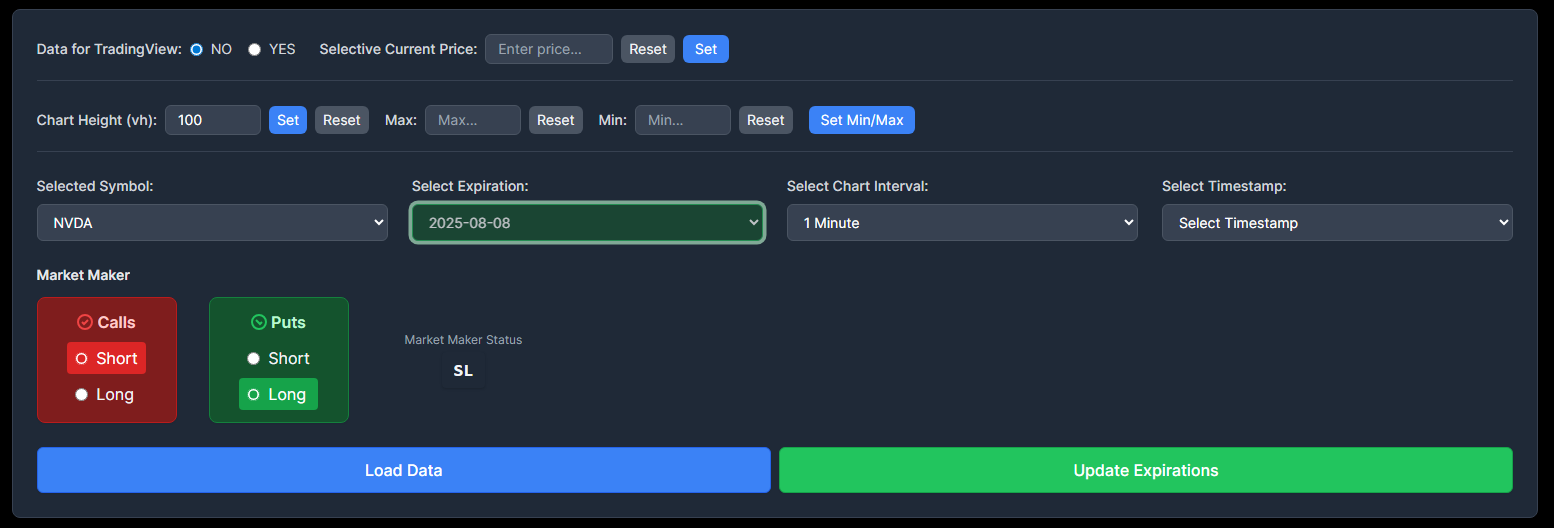
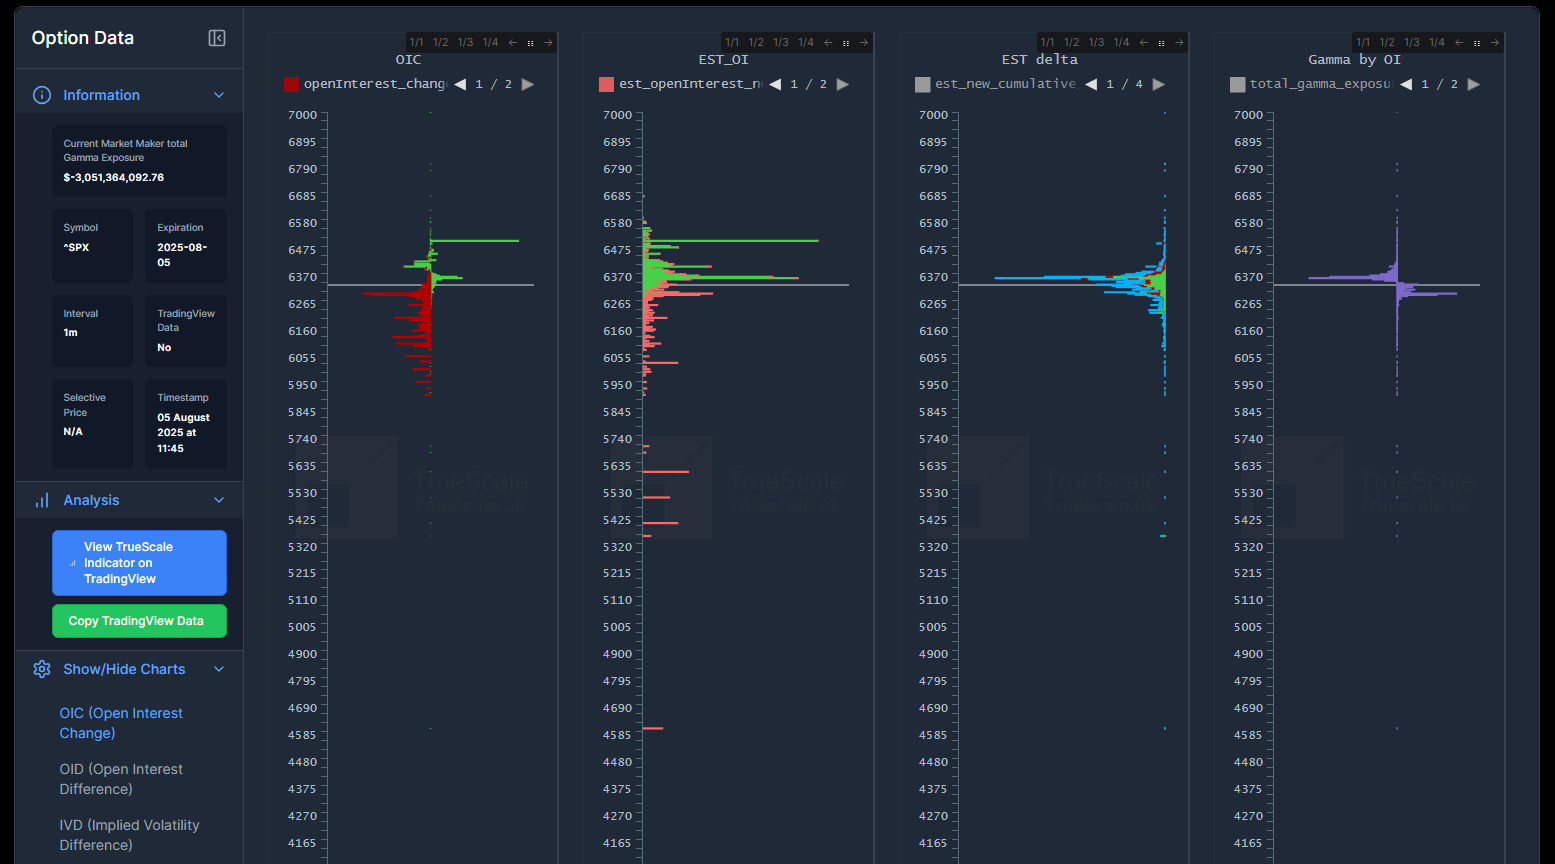
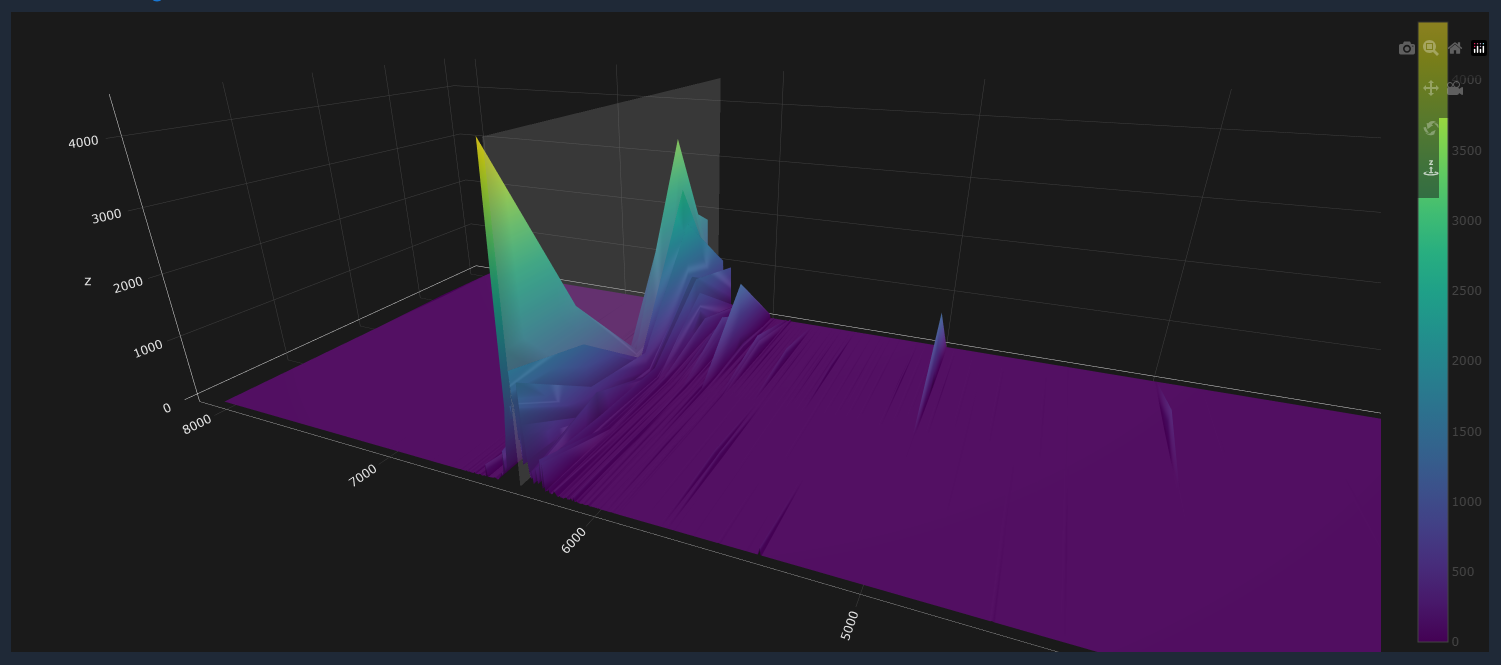
Our Option Trading Dashboard brings together market data and analytical models to help users examine positioning, volatility and potential changes in dealer hedging activity.
These analytical views can help users assess market structure. They should be considered alongside price action, liquidity, volatility and broader market conditions.
Option Greeks measure how an option’s price and risk exposures respond to changes in market variables. They help traders examine sensitivity to price, volatility and time.
Delta measures the estimated change in an option’s price for a one-unit change in the underlying asset, assuming other variables remain constant. Call delta is generally positive. Put delta is generally negative.
Gamma measures the rate of change in delta as the underlying asset price changes. Long vanilla options generally have positive gamma. Short vanilla options generally have negative gamma. Gamma is usually highest near the strike price as expiration approaches.
Vanna measures how delta changes when implied volatility changes. It also describes how an option’s vega changes as the underlying price moves. Its sign depends on the option’s characteristics and market conditions.
Charm measures the sensitivity of delta to the passage of time. It is also called delta decay. Charm can become important near expiration, when time-related changes in option exposure can affect hedging requirements.
Vega measures the estimated change in an option’s price for a one-percentage-point change in implied volatility. Long vanilla options generally have positive vega. Short vanilla options generally have negative vega.
Theta measures the estimated change in an option’s value as time passes, assuming other variables remain constant. Long options often have negative theta, while short options often have positive theta.
Greeks are risk measurements, not independent market-direction forecasts. Their combined behaviour can help explain how option positions may respond to changing market conditions.
| Market Variable | Greek | What It Helps Explain |
|---|---|---|
| Underlying price | Delta | How option value responds to price movement. |
| Change in delta | Gamma | How quickly directional exposure changes. |
| Implied volatility | Vega | How option value responds to volatility changes. |
| Price and volatility interaction | Vanna | How volatility changes can alter delta exposure. |
| Passage of time | Theta | How option value changes as time passes. |
| Time and delta interaction | Charm | How directional exposure changes with time. |
The following examples show how different combinations of price movement, volatility and time can affect option exposure. These are analytical frameworks, not guaranteed price forecasts.
When a position has positive gamma, its delta tends to increase as the underlying price rises and decrease as the price falls. This can create a stabilising hedging effect for the holder of the long-gamma position.
A short-gamma position can require hedging in the direction of the market move. A falling market can increase the position’s negative delta exposure, potentially creating additional selling pressure from hedging activity.
A rising underlying price combined with falling implied volatility can produce competing effects. Delta exposure may benefit from the price move, while negative vega exposure may benefit from the volatility decline. Vanna can influence how delta changes during this process.
A falling market accompanied by rising implied volatility can increase the value of long-option positions in many circumstances. Delta, gamma and vega interact. The actual result depends on strike, expiry, position size and the magnitude of each market move.
As expiration approaches, charm can change delta exposure even when the underlying price does not move. This can affect hedging requirements. The effect can be more significant for options near their strike price.
A sharp change in implied volatility can also change delta exposure through vanna. This means a volatility shock can affect both option valuation and the amount of underlying exposure that requires hedging.
Option prices contain information about market expectations, positioning and risk. By examining volatility, open interest, options flow and Greek exposures together, traders can develop a more structured view of the derivatives market.
Open the Option Trading Dashboard →Options involve substantial risk. The analytical concepts on this page are educational and do not constitute investment advice. Greek values are model-dependent estimates and can change as market conditions change.
Explore the data, analytical models and market views available through the TrueScale Option Trading Dashboard.